
What We Do
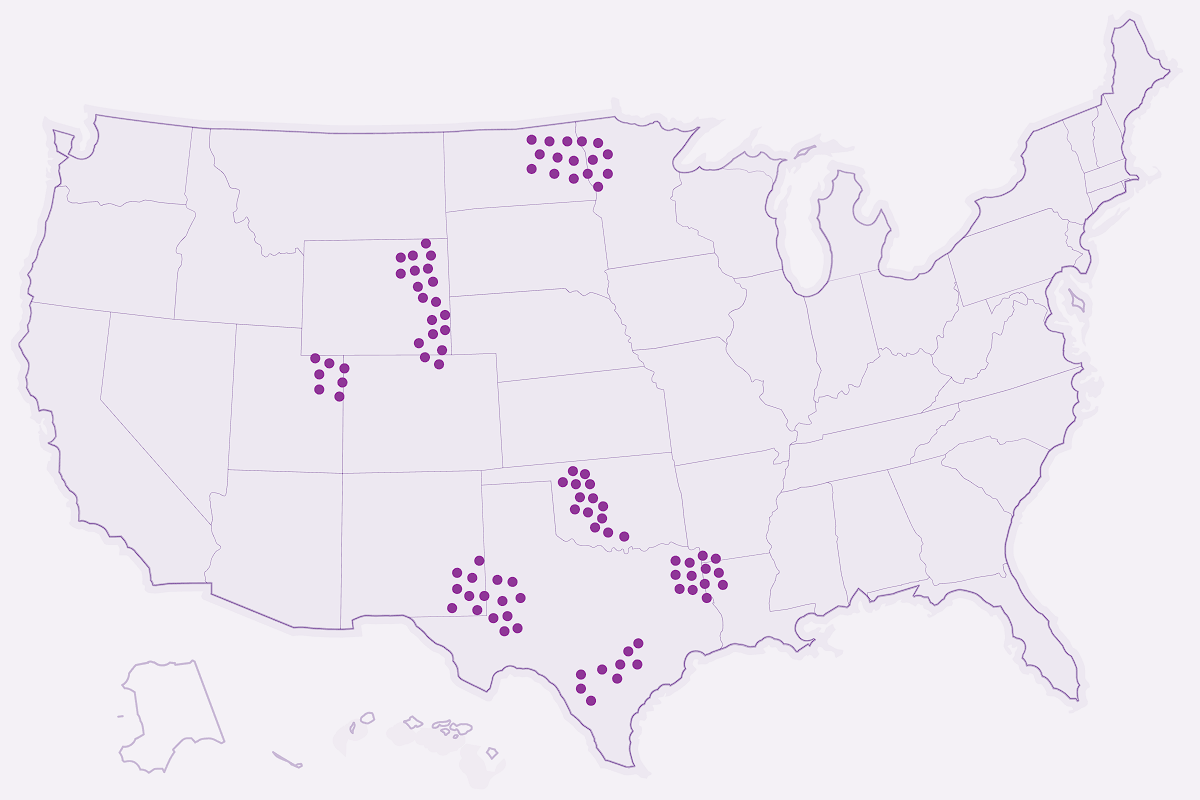
Pheasant Energy is a Fort Worth-based, four-generation acquirer of U.S. oil and gas interests: minerals, royalties, and non-operated working interests across 169 counties in 15 states.
Pheasant Energy is a Fort Worth-based, four-generation acquirer of U.S. oil and gas interests: minerals, royalties, and non-operated working interests across 169 counties in 15 states.

Our team evaluates opportunities through a disciplined process that delivers a firm offer, a clear timeline, and a close on the agreed schedule.

Pheasant Energy has roots back to the 1930s when the first oil and gas rights were purchased in the Moore Family and was carried forward by J. Hiram Moore, Ltd. beginning in the 1950s.
Fracking has disrupted the oil world. Since the dawn of the shale boom less than two decades ago, U.S. daily oil production has surged by more than 175 percent to a record 13.8 million barrels per day (U.S. EIA, 2026). In the U.S., now the world’s top oil producer, average royalty shares of 12.5 percent are reaching 25 percent in high-production regions.
Mineral and royalty rights remain an important part of oil and gas activity in high-producing regions such as the Permian Basin. Property location, lease terms, production history, and ownership details all play a role in mineral rights transactions.
Debt financing is cheap and more readily available to E&P companies. Alternative and structured financing are lending alongside debt capital. These financing vehicles are filling the coffers of junior mining companies actively seeking the next big deal in an active fracking state like Oklahoma or Texas.
The majors are consolidating acreage to improve the production capacity and scale of horizontal drilling. Shell, BP, ExxonMobil and others are buying up property to streamline operations.
Expanded pipeline capacity in the Permian Basin, the epicenter of the U.S. shale boom, has helped ease transportation bottlenecks and support increased oil and gas production. New and expanded pipeline connections serving the Permian, Delaware, and Eagle Ford shale plays have also improved access to key processing facilities and export markets.
Mineral owners can monetize their interests by leasing or selling mineral rights. Less commonly, the owner sells options on the right to buy mineral rights, and even if the options are not exercised, pockets the options fees.
As a fee simple property owner, you may or may not include surface rights with the sale of your mineral rights.
Potential revenue streams from leasing include a signing bonus in exchange for granting the right to explore for minerals and royalty payments if the lessor extracts them.
If your mineral rights are located in a high producing basin, chances are buyers are contracting you directly and making offers.
The best way to ensure you are being offered the maximum market price is to consult other resources.

By listing on a mineral listing service with lots of active buyers and sellers, you can discover what price the market assigns your mineral rights. However – if you enter mineral rights transactions directly, you face many risks, including fraud, counterparty creditworthiness, and so on.
Mineral properties that are auctioned often go for a higher price due to the higher volume of bidders. A reputable auction platform will vet buyers to ensure they are creditworthy and can close the deal.

A broker, who may use either one of these channels, will know how to sell your mineral assets at the best price. An experienced broker will be able to extract more value by strategically aligning your property with the interests of qualified buyers.
Your assets, for example, may be worth more to their oil fracking client who is quietly buying up neighboring interests in New Mexico, North Dakota, Texas, West Virginia and other active basins.
Two offers on the same interest can be far apart. Some buyers price your interest off basin averages or operator projections. Others are brokers who resell it and keep the difference. Your best leverage is knowing how a buyer arrives at its number. Pheasant has been on every side of these deals: as a buyer and as a partner to the operators who drill them.
Our in-house team reviews every acquisition before we commit capital:
Our engineering team builds type curves and decline analysis for your wells instead of relying on operator projections.
We evaluate landing zones, offset well performance and spacing, so the offer reflects what can still be drilled on your acreage.
Our ownership records cover more than 9,500 wells and 7,700 tracts across 15 states.
Our CFO reviews the economics, and our investment committee makes the final decision.
The leasing model is commonly used in the oil and natural gas industry. The biggest drawback is royalties will not be paid if the mine is not productive. And even if minerals are found, producing them could be uneconomical.
 Receive a steady income stream in the form of lease payments (8 to 25 percent)
Receive a lease bonus as a sweetener
Invest proceeds in higher returning asset class
Mineral rights eventually revert to the owner
 Low royalties, if production is low
No royalties, if no minerals are found
Declining lease payouts
Depletion of mineral deposits before lease expiry
Could be locked into low revenue wells and lease extensions for a fixed period
Taxes due on actively producing wells
Large upfront cash payout, regardless of future output levels
Do not assume future price or development risks
Invest proceeds in a higher-returning asset class
May sell rights to minerals in fractions and retain some ownership
Forego future appreciation in mineral assets
Surface land without rights will be worth less in the future
Third-party buyer controls surface rights for E&P activity
How is the leasing and sale of mineral rights taxed?
Another essential difference is taxation treatment. The lease bonus and royalties are treated as regular income for taxation purposes. In contrast, on a sale you will be taxed on the capital gains. For more information, feel free to check our guide on how mineral rights are taxed.
The most considerable risk of leasing is if no production activity takes place, and the lease expires. In this case, full ownership of the rights reverts back to you. In the worst-case scenario, you may no longer have an exit strategy if production cools off and you cannot sell outright at the same high values.
The timing of selling your mineral rights often comes down to your personal financial situation. Whether your assets are producing or non-producing and when they will be producing in the future will impact your future income streams, and ultimately your decision whether to lease or sell your mineral rights.
A change in family asset ownership
Inheritance of mineral property is one of the most common reasons to sell your rights. Divorce and probate family issues are others. The inheritors may choose to monetize their interests for personal finance, real estate or estate planning reasons.
Inconsistent lease payments
Erratic lease payments may not be aligned with your medium-term (house deposit, college savings) or long-term (retirement) savings goals. Selling your mineral assets will allow you to place the capital in lower risk diversified investments.
Fractionalization of mineral rights
Inheritance can fractionalize property ownership across two or more inheritors. This type of distribution often creates conflicts, as well as tax and administration burdens. Alternatively, the mineral interest could be divided up, and each owner can choose leasing or sale as it suits them.
Better market opportunities yonder
You may choose to sell rights on non-producing reserves and invest directly or indirectly in mineral property elsewhere.

Risk tolerance
Can you tolerate income payments streams whose volatility, decline rate and termination dates are undetermined?
Income requirements
Do you require a steady income stream today, or can you wait for future production to come online?
Estate planning implications
Tax implications
Production, drilling and permitting activity on your or adjacent land all minimize the degree of unknowns associated with mineral exploration and development and therefore make your rights more saleable. Catalysts to sell could include:
New activity and/or an increase in production activity in a region – Have neighbors started to drill or produce actively?
Favorable financing terms – Low-interest rates make it more economical to invest in and finance E&P projects.
Institutions and asset managers are increasing investment in your region/minerals – If money is flowing into the sector, operators will find it easier to secure financing to increase exploration and development activity.
Royalty trusts – The trusts, who may pay more per royalty acre, will follow closely behind.
New extraction technologies – Horizontal drilling and other improved extraction methods are making more projects economically viable.
Thorough due diligence can uncover hidden treasures beneath your earth. The production and price level are key determinants in mineral leasing valuation.
Still, most of the time mineral rights value remains under the ground, untapped due to inefficient due diligence. Your interests may be worth more than you have assessed, and be more saleable in the current market.
New technologies that may provide the opportunity to improve extraction, and tap into more and larger payment streams
Adjacent drilling permits that may be encroaching on your reserves, for which arrears may be due
Active production that may be occurring but is not captured in lease payments
Loopholes in complex leasing and purchase agreement terms – leading to unfair cost allocation, for example – that may result in your full producing share in mineral leases not being paid
Conflicts and misinterpretations between federal and state laws
In highly productive areas where valuations are soaring and many wells are being drilled in close proximity, these oversights are more likely to occur.
Misleading contract terms are common. You may be selling royalty interests (royalty acreage), but the fine print is for the sale of both your royalty and mineral interests (mineral acreage).
Lack of knowledge and an unequal playing field can lead to the use of the wrong comparables.
Disguising term deeds and royalty leases as legal rights to minerals are some of the many fraudulent and deceptive activities used by mineral buyers to scam sellers.
Mineral sales are too complex for the inexperienced seller to negotiate the best contract terms.
Conducting proper due diligence on the multitude of factors affecting mineral rights worth takes time.
From shale percentages to royalty payments and shares, all your risks are covered in unambiguous contract language.
The identification of the fair market value and hidden, untapped value will ensure you get the full amount for your mineral rights.
Avoid selling the farm, as the old axiom goes. Sell only to reputable buyers who have passed stringent due diligence tests.
Avoid protracted negotiations and unnecessary concessions – and worst, being duped by a shady mineral rights buyer – by having industry experience behind you.
Our industry experience and network help us provide a firm offer, a clear timeline, and a closing process you can count on.
90+
2.3MM
169/15
$85MM+
1Gross, unaudited results of balance-sheet transactions.
Risks lurk everywhere in mineral asset sales.
At Pheasant Energy, we bring 360-degree insight to oil and natural gas mineral rights sales.
From multiple strategic viewpoints, we analyze a high volume of opportunities at once.
No need to look back with regret when you entrust us to extract the highest value from your mineral rights sales.
Since the 1930s
Pheasant Energy is a Fort Worth based, four-generation acquirer of U.S. oil and gas interests — minerals, royalties, and non-operated working interests across 169 counties in 15 states.
Frequently Asked Questions
Mineral rights bestow ownership of minerals below the surface of a tract of land to explore, develop, and extract the minerals. The owner of the mineral interest may excavate hard rock minerals such as gold or copper, drill an oil and gas well, or surface mine coal.
Considering that the mineral rights can be worth much more than the land they are on, this is a question worth finding an answer to. Many property buyers assume they are gaining ownership of the entire property, both surface and subsurface rights. This assumption is wrong. Generally, a property conveyance transfers rights to both the surface land and mineral reserves below, until the mineral rights are sold. In this case, the mineral rights transfer with the property to you. If you or a previous landowner have not sold the mineral interests, you can sell your mineral rights to an oil and gas company or a trusted mineral rights broker.
Mineral rights agreements entered into by the previous landowners that have not expired are still valid, and you will be obligated under law to honor them. If you neglected to conduct a thorough land and mineral rights search before buying the property, a young inheritor could show up on your doorstep demanding the right to drill oil and gas wells bestowed to his great-great-grandfather and passed down through the generations.
More likely, a large oil company could come calling. They tend to buy up many mineral rights on adjacent lands as future investments. The oil company may be actively drilling on your neighbor’s property. If they have also bought the mineral rights on your property, you could also receive a letter demanding access to explore and drill on your land.
So a property owner can sell the land and the mineral rights, or keep the land and sell the mineral rights. Moreover, the landowner can sell rights to only the oil and gas, limestone, or coal on a tract of land. These rights can be further allocated to specific wells or coal seams, or by separating coal and coal methane; or by surface depth or geographic area, and so forth.
In the case of oil and gas, a lease agreement is entered into between the lessor (mineral rights owner, who may or may not also own the land) and lessee.
The mineral rights give the owner permission to use the surface of the land to access the minerals for exploration and production. Though penalties could be levied and the mineral rights can even be withdrawn if the miner contravenes the surface damage agreement stipulating what types of activities are permissible.
The holders of mineral rights on a property can also lease, sell, and bequeath them as gifts. This way they will pass them down from generation to generation independent of changes in ownership of the attached property.
Also, you have to know that mineral rights and oil and gas royalties come with taxes. You can check our guide on what are mineral rights taxes and how to report oil and gas royalties on tax return.
Every mineral rights broker can also help you sell mineral rights. When choosing a mineral rights sales specialist, ask these questions:
Mineral rights consultants typically have generations of firsthand experience buying and selling mineral rights, and deep contacts in the ‘old boys’ network.
Pheasant Energy, for instance, has grown out of the first purchase of oil and gas rights by the Moore family in the 1930s. Today, we are involved in upstream oil and gas markets and mineral rights management – including leasing, sales, and participation by those with their own interests.
Simple Steps
Give us a call at (817) 251-8282 or use our form in order to take the first step towards getting your offer.